Savings Buckets: Give Every Saved Euro a Job
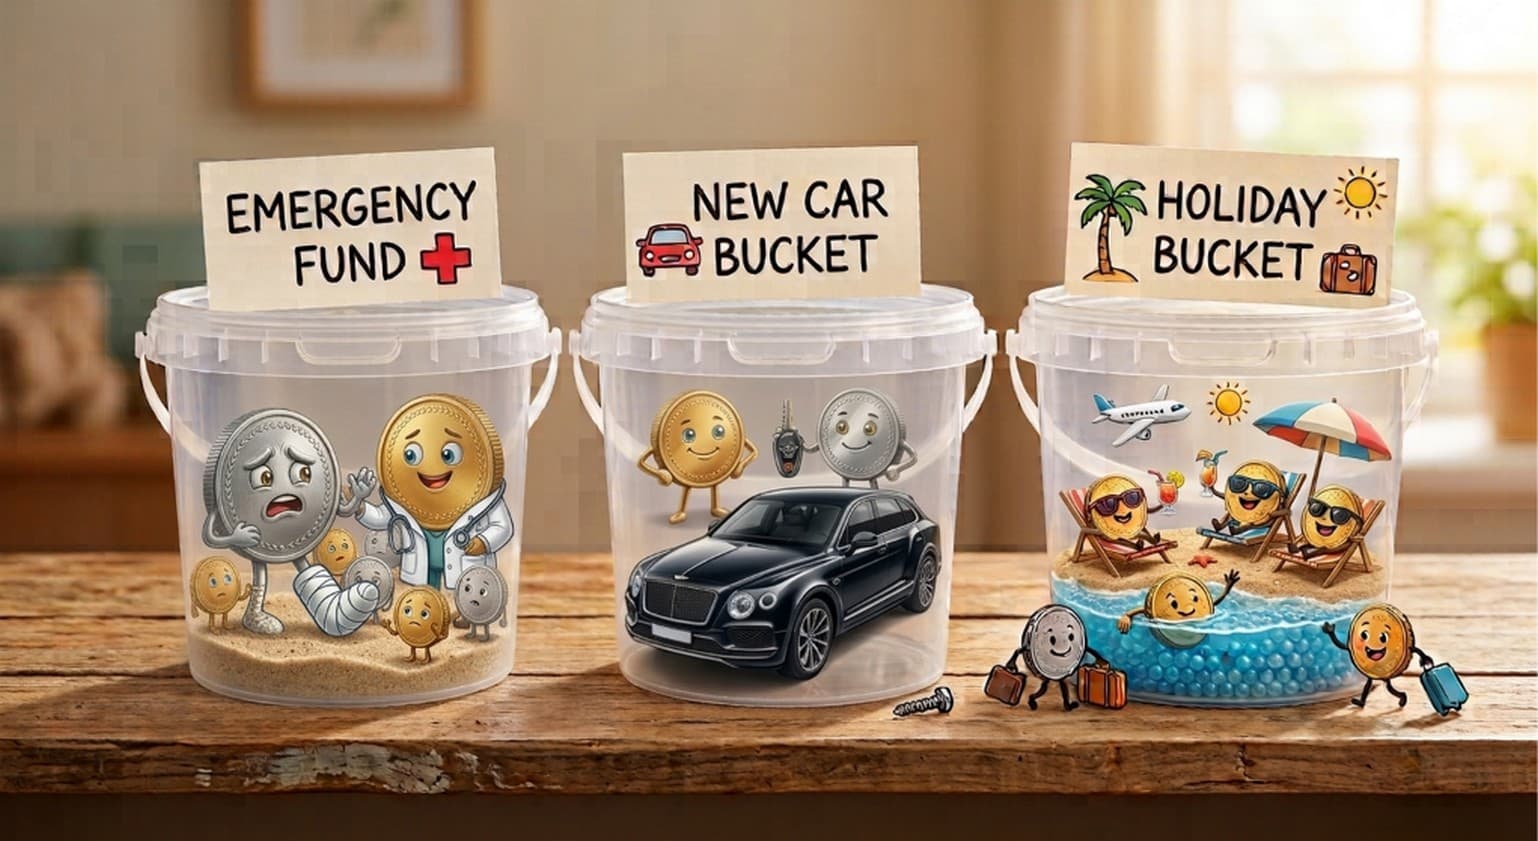
You check your savings account: 4,200 euros. Is that good? It depends on a question the number cannot answer: what is it for? If 3,000 of it is your emergency cushion, 900 is the car insurance due in November and 300 is the start of a trip fund, then 4,200 is not "spare money" at all. It is three promises you made to yourself, sitting in one pile where they are easy to mix up and even easier to raid.
That is the problem with a single savings balance. It tells you how much you have, but not how much you can touch. Savings buckets fix that, and they take about ten minutes a month.
What a savings bucket is
A bucket is a label on part of the money you have already saved: "Emergency fund - 3,000", "Car insurance - 900", "Lisbon in May - 300". The money does not have to move anywhere. The bucket just says what it is reserved for and, ideally, how much you want it to reach.
Two rules follow from that, and the whole system rests on them:
- Buckets do not create savings. You cannot put 500 into a bucket if you have only saved 200. A bucket is a promise backed by real money, not a wish list.
- Buckets do not change your total. Moving money into a bucket, between buckets or back out leaves your savings exactly where they were. Only earning more than you spend (or the reverse) changes the total.
Put simply: the total tells you how much you have, and the buckets tell you how much of it is actually free.
Virtual buckets or separate accounts?
You can do this with several real bank accounts or sub-accounts, or with one account and a list that says who owns what. Separate accounts add a bit of physical friction, which some people like. Virtual buckets are more flexible: you can have six goals without six accounts, and moving money between goals is a note, not a transfer. Both work. What matters is that every euro of savings has exactly one label, and that the labels add up to what is really there.
Why one pile fails
Behavioural economists call it mental accounting: we naturally treat money differently depending on the label we give it. A single balance has no labels, so every withdrawal feels equally harmless. "It's only 150 out of 4,200." Do that six times in a year and the emergency fund you thought you had is 900 short on the day the boiler dies.
Buckets make the label explicit. Taking 150 "from the emergency fund" feels different from taking 150 "from savings", because it is different. That small, deliberate bit of friction sits exactly where you want it.
There is a second benefit. A single goal like "save 10,000" is far away and shapeless. Three buckets with three targets give you three finish lines, and one of them is usually close. Finishing things is what keeps a habit alive.
The buckets most people need
You do not need many. A layout that works for most households:
- Emergency fund. Start with one month of essential expenses, grow it to three or more later. It is filled first and touched last, and only for genuine surprises. If you only ever create one bucket, make it this one. (Our guide on how to build an emergency fund covers the stages in detail.)
- Sinking funds for known bills. Insurance renewals, annual subscriptions, the yearly car service, school fees, holiday gifts. These are not emergencies - you know when they land. A bucket that fills a little each month means the bill is already paid when it arrives.
- One or two wish goals. A trip, a bike, a new laptop. Give it a name and a number. Watching a progress bar creep toward a specific thing is motivating in a way a growing total never is.
- Unallocated. Whatever is left over. Money that is not committed to a goal is not a mistake; it is your flexibility. Just know it is there, instead of pretending it belongs to something.
Four to six buckets is plenty. If you find yourself with twelve, you have stopped organising and started decorating.
Sinking funds: the bucket that pays for itself
Sinking funds deserve a closer look, because they solve the most common budget surprise: the big bill you knew about but forgot.
The maths is simple. Take the amount, divide it by the months left until it is due, and put that much in every month:
- Car insurance, 540 euros, due in 9 months: 60 per month.
- Annual software and streaming subscriptions, 180 euros, due in 6 months: 30 per month.
- Christmas gifts, 400 euros, 10 months away: 40 per month.
That is 130 euros a month for three bills that would otherwise land as 1,120 euros of "unexpected" spending in three bad months. When the bill arrives, you take the money out of the bucket, pay the bill, and the bucket starts again from zero for next year. After one full cycle, these bills simply stop being stressful.
How to fill your buckets
The mechanics are easiest if you work in budget periods (usually a month):
- At the end of each period, look at what you actually saved - income minus expenses. That is your new money. Not what you hoped to save, what you did.
- Allocate it in priority order. The emergency fund until it reaches its current stage, then sinking funds by due date, then wish goals with whatever remains. Leaving some unallocated is fine.
- Write a one-line note with every move. "September salary", "sold the old phone", "paid car insurance". Six months from now the history explains itself.
- Take money out openly. When you spend from a bucket, take the amount out of the bucket and record the expense. Taking it out keeps the bucket honest; recording the expense is what actually changes your total. Skipping either one is how the numbers drift apart.
If your income is irregular
Freelancers, seasonal workers and anyone on commission can use the same system with one change: make a "smoothing" bucket the first priority after a small emergency fund. In good months, part of the surplus goes there; in thin months, you take out enough to cover the gap. Your spending then follows an average income instead of a roller coaster, and the other buckets fill whenever there is something left over.
Saving as a couple
Buckets are also a calm way to handle shared goals. A common setup is "mine, yours and ours": each partner keeps their own buckets, and the shared goals - a holiday, a new sofa, the house deposit - are ones you both can see. Being able to see each other's progress on a shared goal, without merging every euro, removes a lot of "how much did we put aside again?" conversations.
Mistakes that quietly break the system
- Allocating money you have not saved yet. "I'll put 400 into the trip fund because I will save 400 this month." Then the month goes sideways, the bucket says 400, the real savings say 150, and you have two numbers that contradict each other. Only allocate money from periods that are already closed. Buckets are for facts, not forecasts.
- Emptying a bucket below zero. A bucket cannot hold less than nothing. If you need more than is in it, take what is there and cover the rest from Unallocated - or admit the goal needs a bigger target.
- Forgetting the expense side. Moving money out of a bucket without recording the purchase makes your savings look higher than they are.
- Never retiring buckets. When a goal is reached and spent, delete the bucket or rename it for the next goal. Old, empty buckets make the list harder to read and the real goals harder to see.
- Trusting the numbers without checking them. Once a month, compare your savings with your bank statement. If something was missed - a cash purchase, a fee - record it, and let the buckets follow the corrected total.
Trying it in My-Money.Report
If you would rather not keep this in a spreadsheet, My-Money.Report has savings buckets built in, and it enforces the two basic rules for you. Your savings are calculated from the income and expenses you record, and the Unallocated Savings card shows what is still free to assign, counting only closed periods. You cannot put more into a bucket than you have saved or take out more than a bucket holds. Couples can share individual buckets with each other, and buckets with the same name are shown together on one card.
Whichever tool you use, start small: one bucket for the emergency fund, with a target you can reach this quarter. The first time an unexpected bill lands and there is already a labelled pile waiting for it, you will see why the total was never the number that mattered.